Tuesday, 6 October 2026European Markets

EU Semiconductor Industry Faces Strategic Challenge as US-China AI Chip Controls Tighten

The Trump administration is considering export permits for GPUs while Nvidia halts H200 chip production, creating uncertainty for European AI infrastructure. The regulatory crackdown on US-China hardware flows exposes Europe's dependency on external supply chains at a critical juncture for AI deployment. European chipmakers and data center operators must navigate intensifying geopolitical pressures without domestic alternatives to cutting-edge AI accelerators.

LM Salvado
LM Salvado

March 15, 2026

EU Semiconductor Industry Faces Strategic Challenge as US-China AI Chip Controls Tighten
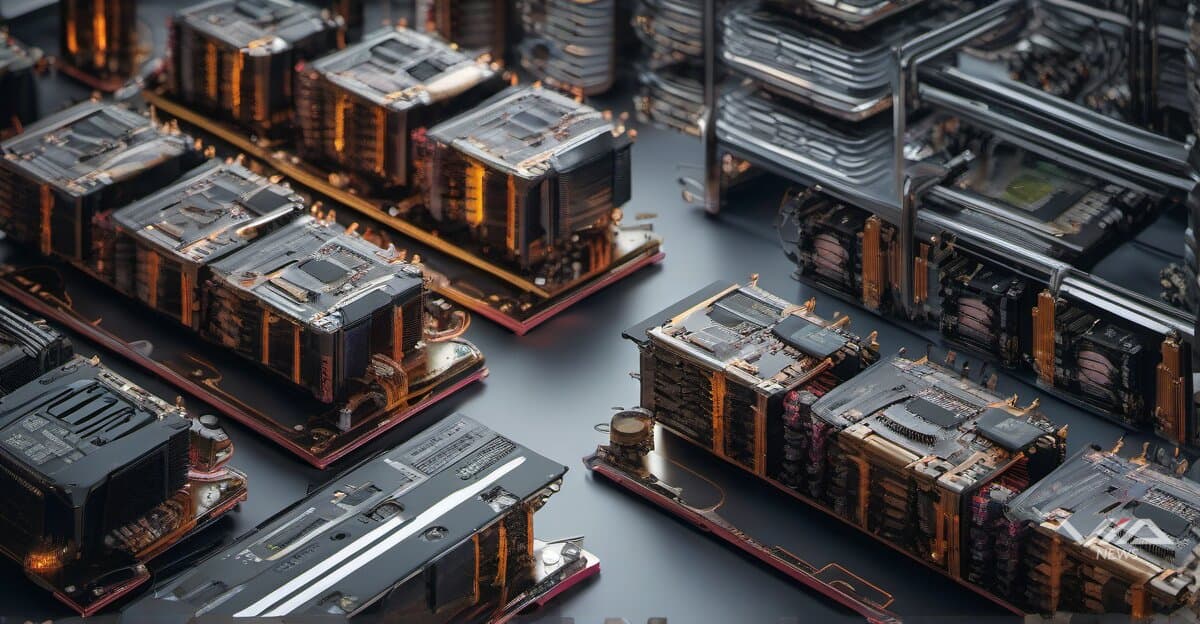
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.
Loading stream...

Nvidia has halted production of its H200 AI chips amid tightening US export controls targeting China, while the Trump administration weighs new GPU export permitting requirements. The moves threaten to constrain global AI hardware availability as European companies scale infrastructure.

Europe lacks domestic production of advanced AI accelerators comparable to Nvidia's H100 and H200 series. ASML supplies lithography equipment to chipmakers worldwide, but no EU-based manufacturer produces training-grade GPUs at scale. This dependency creates strategic vulnerability as US-China tensions reshape supply chains.

The European Commission has prioritized semiconductor sovereignty through the EU Chips Act, allocating €43 billion to boost production capacity by 2030. The initiative targets doubling Europe's global market share to 20%, but focuses primarily on legacy nodes and manufacturing capacity rather than cutting-edge AI chip design.

Major AI labs are simultaneously navigating Pentagon partnerships amid supply chain risk designations. These dual-use technology frameworks complicate European research collaborations and procurement, particularly for institutions receiving US funding or technology transfers.

Broadcom reported strong earnings despite sector uncertainty, signaling continued demand for AI networking infrastructure. The company's custom chip division serves hyperscale data centers, including European facilities operated by AWS and Google Cloud. However, export controls could fragment this supply chain if licensing requirements create compliance barriers.

Neuromorphic computing architectures are emerging as potential alternatives to GPU-based training, with Intel's Loihi and European research initiatives exploring brain-inspired chips. These systems promise superior energy efficiency but remain years from production deployment at scale.

European data center operators face immediate pressure as AI model training demands increase. Without access to latest-generation accelerators, EU-based infrastructure risks falling behind North American and Asian competitors in both capability and efficiency.

The regulatory landscape compounds existing challenges from energy costs and data governance requirements under GDPR. Industry groups are pressing Brussels to negotiate technology access agreements that preserve European AI competitiveness while respecting security concerns driving US export policy.
Source documents

Via News is a conduit. We point to the source documents behind this report — we don't replace them. Trace any claim to its source and decide what to trust. How we source

Source Trace Score1 source document1 with a live linkVerifiability: Basic
  1. [1]News articleYahoo Finance· March 9, 2026
    Tech stocks today: OpenAI's robotics leader resigns after Pentagon deal, Anthropic prepares to battle ban

In this story · Knowledge Files

LM Salvado
LM Salvado

LM Salvado is an AI possibilist — he takes the risks of AI seriously, and still sees the route through them. Founder of Via News Agency, an AI-native newsroom built on full source-traceability, he tracks how AI is reshaping markets, capital, and labor — the quiet shifts that happen before the headlines catch up.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
Obesity and Immunology Readouts, Big Pharma M&A and AI-Designed Drugs Converge Into a Q4 2026 Catalyst Wave
Late-stage data and deal activity are clustering ahead of Q4 2026. Novo Nordisk's CagriSema won Best Abstract at EASD 2026 for its brain and body (fMRI/MRI) data, Lilly showed ADtouch results for EBGLYSS and agreed to buy Merida Biosciences for $2.9B, and Merck's tulisokibart hit its Phase 2b endpoints. A key regulatory catalyst follows: the FDA PDUFA date for the ivonescimab BLA on 2026-11-14. AI-designed rentosertib showing anti-aging effects adds a speculative AI-drug-discovery thread, while QAIAx's microcities trial and QIII pilot (planned 2027-01-01) are peripheral, forecast-only items.
Our read on the data ›
Signals we're tracking
Satellite-Terrestrial Network Integration Acceleration
Increased investment and launches in hybrid satellite-cellular networks across telecom industry; competitive responses from other carriers; regulatory activity around satellite spectrum; expansion of emergency/rural connectivity use cases
Patterns we're watching ›
Where sources disagree
ING Group
Both facts record the same metric (shares_outstanding) for ING Group at the identical observation date (2025-12-31). FACT A states 2,902,437,688 shares; FACT B states 2,902 million shares (2,902,000,000). The difference is 437,688 shares (~0.015%). This is a genuine value conflict, though the discrepancy appears to result from FACT B rounding to the nearest million while FACT A provides the precise count.
We flag conflicts openly ›
Recently verified
✓ Checked against the original source
4,985
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,985 facts checked against source5,351 source documents archived
Query this data → isubstrate.com